.png)

India's Foreign Capital Exodus: A Wage Story, Not Just a Confidence One
Why are record corporate profits failing to translate into new factories, and can consumption sustain growth when workers receive a shrinking share of the value they help to create?
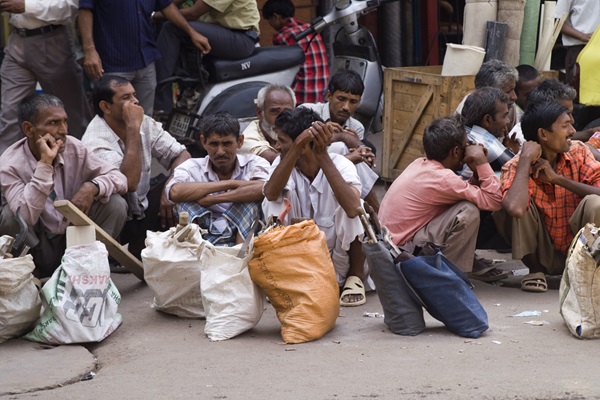
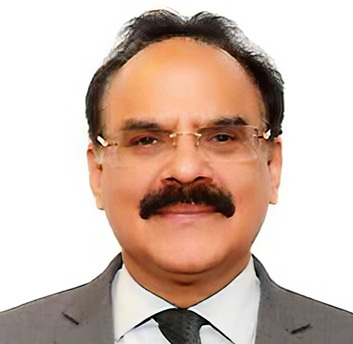
Dr Arvind Mayaram is a former Finance Secretary to the Government of India, a senior policy advisor, and teaches public policy. He is also Chairman of the Institute of Development Studies, Jaipur.
October 8, 2026 at 4:25 AM IST
Foreign portfolio investors pulled close to $19 billion out of Indian equities in calendar 2025, the second-largest annual outflow on record. By September 2026, outflows for the year had already crossed $35 billion, putting 2026 on course to be the worst year for foreign portfolio capital in India's history. Add the near collapse of net foreign direct investment over the same period, from close to $28 billion in 2022-23 to under a billion in 2024-25, and the capital account tells a consistent story of foreign capital withdrawing from India even as the government reports growth above 7%.
The more revealing fact is not how much has left. It is where the capital that remains has chosen to go. Through the first half of 2026, foreign investors pulled roughly $5.9 billion out of consumer stocks, FMCG, durables, consumer services and automobiles, while putting nearly $3.9 billion into capital goods and metals. That is capital inside India voting against the consumption story and for the investment story, inside the same portfolio, at the same time. It is a more precise signal than the aggregate outflow number, because it tells us what foreign investors believe about India's growth composition, not just its growth rate.
The usual explanation is a loss of confidence, driven by rich valuations, a weakening earnings outlook, and global forces such as high US bond yields and a rotation toward the AI theme in Taiwan and Korea. All of that is real. But it does not explain a puzzle sitting underneath it. India Inc's profit-to-GDP ratio hit a 15-year high in 2023-24, even as private corporate investment fell to about 10% of GDP from 11% the year before, well below the 16-17% reached in the mid-2000s. Firms are not short of cash. The 2019 corporate tax cut, intended to free up resources for fresh capacity, instead coincided with a surge in share buybacks and dividend payouts. Firms that can make more money from assets they already own have had little reason to conclude they should build new ones.
This is where the standard confidence story runs out of explanatory power, and where the sharper diagnosis lies. Record corporate profits and stagnant private investment are not two separate puzzles. They are the same fact, read correctly. The profit-to-GDP ratio rose not primarily because companies sold more, but because the share of value added going to wages fell. In organised manufacturing, the wage share of value added declined from 22.2% in 2000-01 to 13.7% by 2023-24, even as output per worker more than doubled over roughly the same period. Profit growth driven by paying labour less relative to output is a fundamentally different signal to a company's own management than profit growth driven by selling more to a growing market. The first does not tell the management that a new plant will find buyers. The second does. India's recent profit boom has been closer to the first kind than the second, and that is precisely why it has not converted into capacity expansion despite five years of tax incentives and production-linked subsidies designed to make exactly that conversion happen.
The same wage compression explains why consumption growth has been disappointing enough to worry foreign investors in the first place. Private final consumption expenditure growth slowed from around 11.7% in 2021-22 to about 7.6% in 2024-25, even as GDP kept printing above 7%, because wages, the main channel through which output growth reaches household income, have simply not kept pace. Rural wage growth, once the headline numbers are adjusted for a recent change in sampling methodology, comes out closer to 4% nominal growth against inflation running at 4-6%, meaning real rural purchasing power has been flat to falling. White-collar salary increments have settled near 9%, barely ahead of inflation and well below the double-digit raises of the previous decade. A workforce whose pay has not kept pace with the output it produces cannot be expected to drive the kind of consumption growth that would, in turn, justify fresh private investment.
Foreign investors appear to have worked this out faster than much of the domestic commentary has. Their shift away from consumption stocks and into capex and infrastructure stocks is essentially a market-credited version of the same diagnosis economists have been considering for two years, though without explicitly identifying its mechanism. UBS has made this diagnosis explicit, calling the slowdown structural rather than cyclical and pointing to earnings moderation spreading to defensive parts of the economy, such as consumer staples, which are ordinarily the sector most insulated from cyclical demand fluctuations. It also flags Indian equities trading at a 72% premium to the rest of the emerging-market universe, a premium that becomes difficult to defend once the earnings behind it stall. S&P-Crisil's data from this month sharpens the point: net FPI inflows fell 16.6% in 2025-26, while gross FDI of $94.5 billion collapsed to net inflows of just $7.8 billion once repatriation and outward investment are netted out, a gap too wide even to finance a current account deficit of 0.6% of GDP. What makes this moment more serious than the usual cyclical scare is that the government's own capital expenditure, which has been substituting for weak private investment and weak consumption for the better part of five years, is itself now running into its fiscal limits, with non-defense capex growth projected to slow sharply in the second half of this fiscal year. The engine that has been carrying India's growth composition on its own is losing power at precisely the moment private investment and consumption would need to take over.
None of this means India's growth rate is a fiction. It means the growth is being driven by a narrower set of engines than the headline number suggests, and that foreign capital, rightly or wrongly, has started pricing the gap between the two. Until Indian wages rise in line with the productivity gains firms are already capturing, record corporate profits will keep showing up in balance sheets rather than in new factories, and the capital that has already left will have little reason to return.
(This is the first of a two-part series examining why India’s strong GDP growth coexists with weak consumption, subdued private investment and foreign capital outflows. The second part will assess whether policy responses add up to a coherent strategy for rebalancing growth.)
More From BasisPoint