.png)

Venkat Thiagarajan is a currency market veteran.
November 4, 2026 at 6:24 AM IST
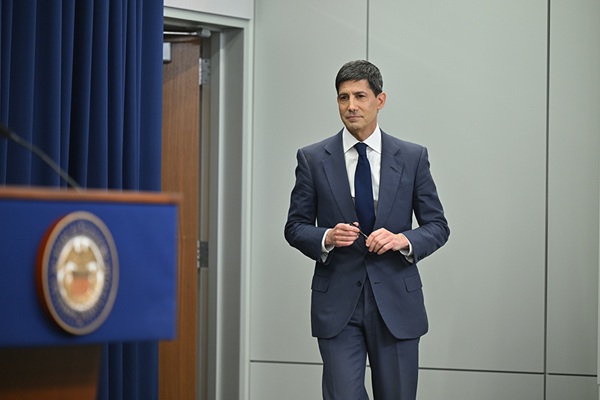
Kevin Warsh’s most visible changes at the Federal Reserve concern how it communicates with financial markets. Shorter statements, less guidance on future interest rates and his withdrawal from the projections exercise have altered that relationship. After four policy meetings, the emerging test is whether this restraint gives the Fed greater flexibility while helping markets interpret its decisions.
Warsh’s pre-chairmanship policy preferences can be grouped into a “WARSH” framework:
-
Withdrawing from forward guidance.
-
Anchoring policy to realised inflation measures.
-
Reducing the balance sheet.
-
Simplifying communication.
-
Hawkish inflation discipline.
These preferences provide a useful basis for assessing his early record, although their implementation has progressed unevenly. The clearest changes concern guidance and communication. The broader ambitions involve choices about policy formulation and the Fed’s operating framework whose consequences will take longer to establish.
Forward guidance acquired particular importance during the global financial crisis, when near-zero interest rates constrained conventional easing. Indicating that rates would remain low helped central banks influence longer-term borrowing costs and economic activity. Its effectiveness depended on shaping expectations about decisions that had yet to be taken.
The case for restraint becomes stronger when uncertainty makes a precise policy path unreliable. Investors may give conditional projections more weight than policymakers intend, allowing an indication of likely action to acquire the force of a commitment. A necessary response to changing circumstances can then appear inconsistent with earlier assurances.
Reducing those assurances could give the Fed more room to reassess incoming evidence. Investors would carry greater responsibility for judging what the data imply, with less confidence that earlier guidance would continue to describe the likely policy path. The potential value of constructive ambiguity lies in encouraging that independent assessment while preserving the Fed’s freedom to revise its judgement.
Market Signals
The demand for policy signals persists even when the chair becomes less willing to supply them. Investors still have to value bonds, assess borrowing costs and decide how much interest-rate risk to bear. Dissenting votes, meeting minutes and individual officials’ remarks can consequently acquire greater weight in forming expectations.
October’s decision to hold rates drew two dissents in favour of an increase, giving investors information about disagreement within the committee. Minutes can reveal more of the reasoning behind such differences. Reading these signals still requires judgement: they describe assessments made at a particular meeting, against information that will continue to change.
The chair also speaks for a committee whose members retain their own assessments and public voices. If their speeches and interviews continue while the chair offers fewer indications, markets may attach disproportionate importance to individual interventions. The resulting message could become more fragmented even as formal communication becomes more concise.
Warsh’s decision to withhold his personal projections illustrates the distinction between communicating less and changing how policy is made. His colleagues continue to submit forecasts. His abstention establishes a position on public guidance; it does not show how much weight forecasts carry in the committee’s deliberations.
Monetary policy works with lags, requiring judgements about conditions beyond the latest inflation reading. Greater attention to observed outcomes can discipline those judgements, especially when forecasts repeatedly disappoint. It cannot remove the need to assess how a decision today might affect inflation and employment later.
The revised meeting calendar reflects a related effort to change deliberations. Eight annual meetings will remain, with one devoted to strategy in 2027 and two expected in 2028. Warsh’s stated aim is to reserve more time for questions extending beyond the immediate rate decision. The change makes strategic deliberation a more explicit part of the committee’s work.
Policy Tests
The balance sheet exposes the practical constraints on a wider transformation. Warsh’s preference for a smaller portfolio must be reconciled with the reserves required for orderly money markets. The funding strains of 2019 remain a reminder that reducing the central bank’s footprint can create operational difficulties if reserves become scarce.
The Fed ended securities runoff in December 2025. Its current instructions provide for reinvestment of principal payments and purchases when appropriate to maintain ample reserves. The balance-sheet task force must examine how far the portfolio can shrink while meeting those operating needs. Resolving that question would give the ambition of a smaller Fed footprint a practical foundation.
Inflation discipline also requires assessment through decisions and outcomes. Warsh has emphasised restoring inflation to the 2% target, and the September increase of 25 basis points provides evidence of action. A fuller judgement will depend on how the Fed responds when inflation, employment and financial conditions present conflicting pressures.
Those choices also connect inflation discipline to communication. Explaining why particular risks justify action, or why more evidence warrants waiting, would give investors a basis for assessing policy without requiring a projected timetable. Credibility would rest on consistency between the Fed’s stated priorities, its reading of the evidence and its decisions.
The WARSH framework therefore describes an agenda whose communication elements have advanced more visibly than its operational ambitions. Its relevance to other central banks will depend on whether reduced guidance improves the quality of policy and market interpretation, rather than on the appeal of shorter statements.
Warsh’s opportunity is to make the considerations governing policy clearer while offering fewer assurances about its future course. Constructive ambiguity would then encourage markets to study the economy more closely and give the Fed room to adapt. Its success will depend on whether investors can understand those adaptations without becoming more reliant on scattered policy clues
More From BasisPoint