.png)

Vivek Kaul is a writer and an economic commentator.
September 18, 2026 at 3:27 AM IST
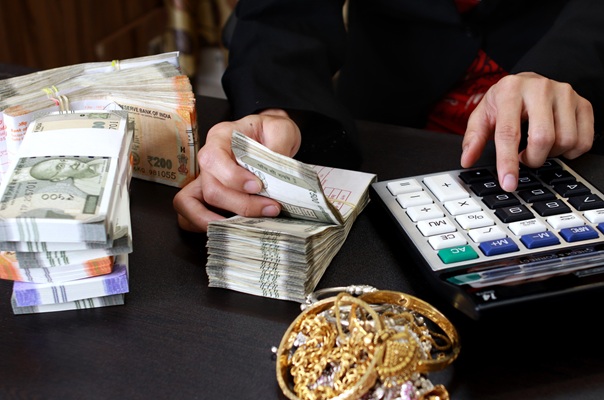
Gold loans, or loans against gold jewellery, have been quite a success story for banks as well as non-banking finance companies – or at least we have been told so.
As of July 2026, the latest data available, the total gold loans given by banks and non-banking finance companies stood at ₹9.1 trillion, up 80% from July 2025 and 235% from July 2024. (This piece is limited to retail gold loans.)
These sensational figures do not really tell us the overall story simply because there are even more sensational figures on offer.
Third, gold loans have emerged as the largest segment within non-housing retail loans, growing at 42.4% per year between March 2024 and March 2026 – much faster than overall non-housing retail loans, which grew at 23% per year during the same period.
Indeed, both banks and non-banking finance companies are giving out gold loans at a very fast pace.
Why?
If one were to speak to those in the business of giving out these loans, they are likely to offer the following reasons.
First, the price of gold has gone up over the last few years. This means that a larger loan can be given against the same amount of gold.
Third, some new kids on the block are also likely to get Gen Z and millennials into their conversation, and say stuff like, “The current generation is not as emotionally attached to gold as their parents and grandparents were.”
Fourth, the rise of the unified payment interface, or UPI, has made it easier for lenders to figure out the repayment capacity of a lot of people working in the informal sector. This has helped finance the working capital requirements of the self-employed and very small entrepreneurs through gold loans.
For non-banking finance companies, gold loans have gone up by ₹2.1 trillion between July 2024 and July 2026, whereas other loans – of which personal loans are a part – have contracted by more than ₹164 billion.
So, the lenders are lending more against collateral – which is gold – and that’s good for them.
In fact, the RBI Financial Stability Report published in June 2026 points out that the average loan-to-value ratio of gold loans of banks fell to 55.4% in March 2026 from 62.4% a year earlier. For select non-banking finance companies, the ratio fell to 59.9% from 60.7%.
The regulatory loan-to-value cap ranges from 75% to 85%, depending on the size of the loan. In case gold prices fall substantially, the lenders will have some legroom to work with.
All these are plausible reasons for the boom. Nonetheless, the funny thing is that none of those giving out gold loans think that financial distress is also a strong reason for the recent popularity of these loans.
And that’s understandable. Nobody selling loans wants to tell you that financial distress is helping drive their business.
Let’s see what data tells us.
First, the RBI’s Financial Stability Report points out: “The recent increase in gold loans is driven primarily by existing borrowers, who are using higher gold prices to secure larger loans and roll over existing debt.”
What the RBI is saying is that many borrowers are taking on newer gold loans to repay existing loans. So, part of the gold-loan boom is not fresh borrowing for fresh economic activity, but borrowers using more valuable collateral to borrow more and ensure that they don’t default on earlier loans.
The question is how long can this continue?
Second, as per the Gold Loan Landscape Report published in April 2026 by TransUnion CIBIL, a credit bureau, the share of originations coming from ETGL (Existing-to-Gold-Loan) borrowers – people who already had a gold loan and are taking another – has been on the rise – from 76% in 2022 to 83% in 2023, 86% in 2024 and 90% in 2025. The share going to new-to-gold-loan borrowers fell from 24% to 10%.
Third, as Bhavesh Jain, MD & CEO, TransUnion CIBIL, said in a recent interview to The Hindu Business Line, one in every five gold loans goes to a borrower who already has another loan that has turned into a non-performing asset.
Fourth, as the Gold Loan Landscape Report, points out: “For a section of stressed borrowers, gold loan has become the product of last resort.”
This reiterates the third point.
Fifth, and this is the most important point of this piece, as per the Economic Survey 2024-25, the average real monthly income of male self-employed workers fell 9%, from ₹9,454 in 2017-18 to ₹8,591 in 2023-24. For female self-employed workers, it fell by a third, from ₹4,348 to ₹2,950.
Self-employed workers account for around 56-58% of the workforce.
Among salaried workers, average real monthly income fell 6.4% for men, from ₹12,665 to ₹11,858, and 12.5% for women, from ₹10,116 to ₹8,855.
Salaried workers account for another 21-24% of the workforce.
Put these together, and the categories accounting for close to four-fifths of the workforce have seen their average real incomes shrink. In other words, incomes haven’t kept pace with the price rise.
Indeed, when incomes are under pressure, borrowing against the family gold can become an easier way of raising money to meet regular expenses.
There is a larger point here as well: Household debt had reached 45.5% of GDP by September 2025, the highest level ever, with consumption loans being the main driver.
In other words, the gold-loan boom is happening against a broader rise in household borrowing and household debt.
For some households, it may simply be a way of raising money when other options are limited. The lenders may be celebrating record growth, but the family chest is perhaps running on empty. And that’s something worth thinking about.
More From BasisPoint