.png)

Groupthink is the House View of BasisPoint’s in-house columnists.
October 2, 2026 at 5:13 AM IST
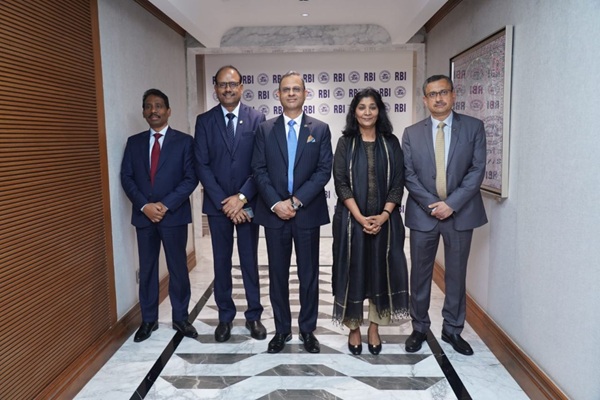
The Reserve Bank of India looks set to raise interest rates next week. The important question is what it wants the rate hike to accomplish.
Is this a backwards-looking adjustment to financial conditions that have already tightened, or the first step in a forward-looking campaign to force inflation back towards 4%?
The RBI is behind the curve as the repo rate remains at 5.25%, while the benchmark 10-year government bond is around 7.2%. They need not converge, but investors have already repriced inflation, global rates and the compensation they demand for holding long-duration debt.
A 25-basis-point increase could therefore be little more than an acknowledgement of a changed world.
Or it could be the first instalment of something larger: a willingness to keep raising rates, drain liquidity and maintain restrictive conditions until the inflation outlook has materially changed.
The first hike may look identical in both cases. The objective would not be.
Policy Purpose
True, those numbers remain within the 2-6% tolerance band, and much of the pressure comes from food, fuel and other supply-side forces, which are immune to higher rates. But monetary policy matters when those shocks begin to shape wider pricing behaviour and expectations, turning first-round price increases into broader inflation.
So what is the RBI trying to do? If the aim is simply to recalibrate a policy rate that has become too low relative to prevailing conditions, one or two measured moves may suffice. If the aim is to return inflation durably to 4%, the relevant questions are how restrictive rates must become, how quickly they get there and how long they stay there.
Is the RBI correcting yesterday’s policy rate, or trying to determine tomorrow’s inflation rate?
Growth Cushion
If the RBI itself believes the economy’s underlying growth potential has strengthened, how much weight should the Monetary Policy Committee place on shielding growth from higher rates? An economy expanding near 8% provides a cushion for tightening that might not exist later, when growth has slowed, but inflation has become more entrenched.
The external backdrop narrows the room for hesitation further. Oil is above $100 a barrel, the rupee is around 96 to the dollar, and global rates remain elevated. None requires the RBI to follow the Federal Reserve or defend a particular exchange rate. Together, however, they raise the cost of tolerating persistent inflation.
Market Signal
The distinction is between the size of the first hike and the scale of the cycle. If inflation remains around 5.5% while growth stays above 7%, does 25 basis points become 50, 75 or 100 basis points of cumulative tightening? Just as importantly, what would make the RBI stop?
Liquidity will offer another clue. The banking system has recently been in substantial surplus, while the RBI has used variable-rate reverse repos and bond sales to absorb liquidity. If tightening is meant to bite, those operations should reinforce rather than dilute the signal from the repo rate.
Staying Power
A central bank serious about inflation does not need to announce its terminal rate in advance. It does need to make its reaction function believable. If inflation requires another hike, markets, households and businesses must believe that another hike will come, even when the arguments for stopping become louder.
So the first increase is not really the test. A catch-up hike looks backwards, validating a tightening that markets have already imposed. An inflation-fighting hike looks forward, using rates, liquidity and communication to alter the path of prices.
Next week’s decision may tell us that the RBI has changed direction. What follows will tell us what it is actually trying to achieve.
More From BasisPoint