.png)

Vivek Kaul is a writer and an economic commentator.
October 21, 2026 at 3:07 AM IST
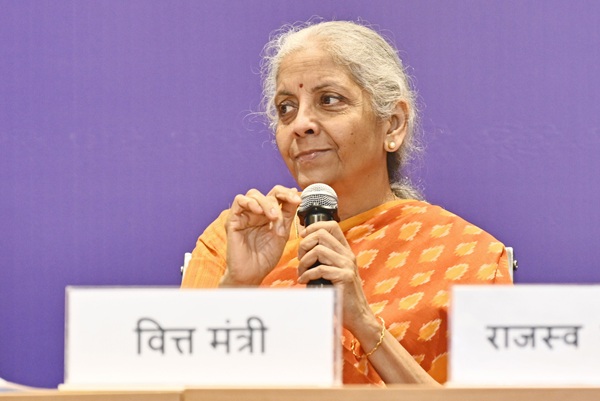
Sometimes, what seems like a complicated truth, can be summarised in just one line. Which is what the Indian Finance Minister Nirmala Sitharaman recently did, when she said: “Because of the ease of liquidity, ease of availability, people are even exiting easily.”
She was explaining why foreign institutional investors have been exiting Indian stocks in droves.
The FIIs have net sold stocks worth ₹4.9 trillion or $53 billion since April 2024 – the start of financial year 2024-25. In calendar year, 2026, they have net sold stocks worth ₹3.1 trillion or $33 billion.
Now, for sellers to be able to sell, the buyers need to be in the mood to buy. If the buyers are not in the mood, the sellers need to offer a lower price to incentivise the buyers.
If the buyers are still not in the mood, the sellers need to offer an even lower price.
This is how a market works until the buyers start buying or the sellers decide to hold back from selling.
Now, the sellers, that is the FIIs in this case, understand this. And unless they are really desperate to exit, they won’t crash the Indian stock market.
In the last few years, as the FIIs have sold, the stock market has fallen a little, but it hasn’t crashed.
The FIIs have mostly invested in large-cap stocks over the years. As of June 2026, the latest data available, their ownership in Nifty 50 stocks fell to a fourteen-and-a-half-year low of 21.1%.
At the same time, from its then all-time high level reached in late September 2024, the Nifty 50 index has fallen a little under 13%. For the massive selling carried out by FIIs that’s not much of a fall.
This has happened because Indian retail investors have been happy to buy what’s being sold by FIIs. The net inflows into equity mutual funds stood at ₹4.2 trillion in 2024-25 and ₹3.5 trillion in 2025-26. From April to September 2026, the net inflows into these funds have stood at ₹1.8 trillion.
So, from April 2024 to September 2026, the net inflows into equity MFs have been ₹9.5 trillion.
Indeed, not all of this money has gone into buying Indian stocks, but a bulk of it has. Also, the money being invested into equity MFs, need not necessarily be going into large-cap MFs, which are mandated to invest a bulk of the money they collect into large-cap stocks.
But given that the Nifty 50 stocks form close to 54% of the free-float market capitalisation of stocks listed on the NSE, there is no way fund managers can avoid buying these stocks, even when money is being invested in non-large-cap MFs.
Further, even more retail money has come into the stock market through insurance schemes and government pension and provident funds like National Pension System, the Employees’ Provident Fund and more.
Beyond this, retail investors have also bought stocks directly. There has been an explosion in the number of demat accounts post the pandemic.
The Selling Math
The FIIs have net sold ₹4.9 trillion worth of stocks from April 2024 till date. The retail inflows have been significantly more than this amount.
The solid retail inflows have not just allowed FIIs to sell, the promoters of Indian companies have also taken this opportunity to take some cash off the table.
The ownership of private promoters in stocks that make up for the Nifty 50 companies has fallen from around 29.8% in March 2024 to 27.1% in June 2026.
When promoters sell, it tells us that they believe that their businesses are not worth as much as the stock market thinks they are. Hence, it makes sense for them to cash in at a higher price.
The retail inflows have also allowed many companies to list on the stock market through IPOs at extremely high valuations, allowing promoters and venture capitalists to make a killing. This includes many startups which hope to make some money someday.
So, that explains how all this selling has been absorbed without the market really crashing. This is the great Indian wealth transfer, from retail investors to the hyper-rich fat cats.
But it doesn’t explain the ease of liquidity and the ease of availability that the finance minister Sitharaman talked about.
The Ease of Availability
There are three major factors which explain the ease of availability or the fact that an investor can buy or sell a stock or an equity MF almost anytime and anywhere.
The cost of internet bandwidth has fallen over the years. So has the price of smartphones. Stock brokerages have also launched several low-cost, easy-to-use apps.
This has made the process of buying and selling easier and very smooth. One does not need to be near a personal computer or a laptop to buy or sell a stock or a mutual fund.
Also, anyone who has used the websites of legacy stock brokerages to buy and sell stocks knows how complicated things could get. Further, one doesn’t have to deal with a mutual fund agent or an insurance agent to invest. This has led to the rise of the do-it-yourself investor.
This explains the ease of availability.
What About the Ease of Liquidity?
Once the pandemic started, the interest rates available on fixed deposits fell. Further, the tax advantage of debt mutual funds against fixed deposits was done away with from April 2023 onwards.
This pushed a chunk of retail investors towards stocks and equity MFs in search of higher returns.
Also, once stocks and MFs had delivered high returns, a deluge of retail money began flowing into them from April 2024 onwards.
Of course, during and post the pandemic, young financial influencers took off. They sold the idea of investing in stocks and their derivatives to their followers as a one-way ticket to the moon. What they did not tell us is that they had quietly been doing affiliate deals with stock brokers and were being paid to say what they were.
The rise of smartphones and cheap internet ensured that many people in the business of managing other people’s money, the OPM wallahs that is, were able to turn themselves into brands. Brands, whose messaging, the retail investors bought. This essentially cashed into the tribalism of human beings, where we want to do what everyone else around us is doing.
The only message that the OPM wallahs drove home was to buy, buy and buy more. All this also led to the ease of liquidity.
Further, the Mutual Funds Sahi Hai campaign caught the attention of retail investors everywhere and led to the rise of investing in equity MFs through systematic investment plans.
The net inflows into SIPs were at ₹927 billion in 2018-19, before the pandemic started. They peaked at ₹3.5 trillion in 2025-26. From April 2026 to September 2026 they stood at ₹1.6 trillion.
All these factors came together to ensure ease of availability and ease of liquidity. In that sense, Finance Minister Sitharaman is totally right in what she said.
The OPM wallahs have jumped into this and have blamed the taxes on capital gains to explain why the FIIs have been selling.
But these taxes were around even in 2020-21, when the FIIs net bought Indian stocks worth $37 billion. They also net bought stocks worth $25.3 billon in 2023-24. Also, when the stock market was doing well, none of these OPM wallahs had a problem with the taxes.
Now, this is not to say that taxes don’t matter. They do. But they aren’t the only reason that explain the selling.
The major reason FIIs are selling is because they can sell. There are enough and more buyers.
They are selling because all the retail money coming in led to valuations of companies going totally out of whack. The OPM wallahs with their perpetual buy, buy, buy, messaging, are also responsible for this.
Also, a bulk of the FII buying of Indian stocks happened in 2020-21 and the years before that. So, they are clearly sitting on profits.
The Indian Rupee
Now, all the selling by FIIs and venture capitalists (through IPOs) has had a negative impact on the rupee.
When the selling happens, they get paid in rupees. But these rupees then need to repatriated abroad in dollars. This increases the demand for the dollar and leads to the weakening of the rupee.
A weaker rupee hurts the Indian economy in various ways. Of course, the FIIs selling rupees and buying dollars, is happening at a time when India needs more dollars to pay for oil, gas and fertiliser imports. The prices of these commodities have gone up due to the war in West Asia.
At the same time, the net foreign direct investment, which brings in dollars into India, has taken a beating over the last few years. Further, software exports, which bring in dollars, have also not grown at the same pace as they used to.
In this environment, the country decided to raise foreign currency deposits, paying higher interest rates to attract dollars from Indians living abroad. This is essentially an attempt to plug the rising demand for dollars.
The Reserve Bank of India has also created a special window to meet the entire daily dollar requirements of the oil marketing companies. The idea is that these companies buy the dollars required directly from the RBI and don’t go to the market and increase the demand for dollars, leading to the further weakening of the rupee.
Over and above this, the RBI has also made hedging more expensive. Further, fresh investments into gold fund of funds, have been stopped. The logic being that these inflows are used to buy gold, which needs dollars. The trouble is that these inflows are really small in the overall scheme of things.
At the same time, the foreign currency assets of the RBI, have fallen from $648 billion on September 4, 2026, to $598 billion as of October 9, 2026. Indeed, the RBI has sold foreign currency worth $50 billion in a matter of just five weeks, in order to prevent the rupee from weakening further and moving closer to the 100-to-a-dollar mark.
So, a lot is being done to prevent the rupee from falling further and to reduce the demand for the dollar. But when FIIs and VCs sell Indian stocks and buy dollars, they add to that demand.
It’s important to tackle this issue as well. How? By disincentivising the excessive flow of money into stocks, both directly and indirectly.
Of course, this is easier said than done. Nonetheless, as I had said in a June 2026 piece:
“One way is to tax all kinds of income at the same rate. Capital gains from the sale of shares or equity mutual funds should be taxed at the same rate as gains from debt mutual funds, interest earned on fixed and other deposits, or gains made from selling gold and real estate.
This will create a level playing field across asset classes and ensure that tax considerations do not disproportionately influence investment choices.”
Further, the period of holding of stocks and equity MFs, to qualify for long-term capital gains, should be increased from the current cut off just one year.
The OPM wallahs will argue that favourable tax treatment encourages investors to invest in IPOs, which, in turn, helps entrepreneurs raise capital for their businesses.
But as I had explained in a July 2026 column, IPOs are increasingly becoming exit routes for founders, venture capitalists and private equity firms, and not really providing growth capital. Regulation must adapt to this.
Over and above this, the OPM wallahs should be asked to tone down their rhetoric of buy, buy and buy more. This can easily be done given that many OPM wallahs are close to the current Union government.
And finally, the government shouldn’t cut the tax on capital gains, at least not immediately. If the retail inflows into stocks continue, this might just encourage the FIIs to sell more, thereby putting further pressure on the rupee.
Once retail flows into the stock market subside, the FIIs will go slow on selling, because no large investor really wants to crash the market and majorly reduce the value of the stocks they still own.
The government wants fewer dollars leaving India. But it also wants retail investors to keep pouring money into stocks, while the OPM wallahs keep shouting buy, buy, buy. These two objectives cannot coexist indefinitely.
Finance Minister Sitharaman is right when she says that the ease of liquidity and availability has made it easier for foreign investors to exit.
But she also needs to recognise the other side of this equation. The government cannot keep encouraging retail investors to pour money into stocks, while the OPM wallahs keep shouting buy, buy, buy, and then express concern when FIIs and promoters walk away with the money and the rupee weakens further.
In the end, it’s as simple as that.
More From BasisPoint