.png)

R. Sridharan is a seasoned business journalist who has worked in India and the US.
September 30, 2026 at 4:20 AM IST
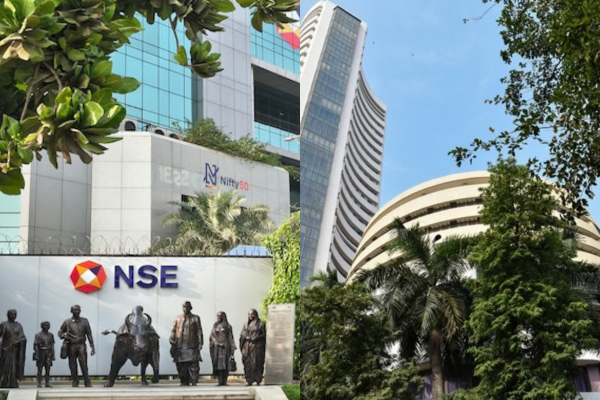
With the National Stock Exchange’s shares now listed on the Bombay Stock Exchange, it is easy to forget what a difficult journey it has been to the public market for the exchange, and how complicated it has been for the market regulator, the Securities and Exchange Board of India.
It was in November 2015, more than a decade after it first considered the idea, that SEBI finally decided to allow India’s stock exchanges to list, but not on their own exchanges. The Bombay Stock Exchange became the first of the two big exchanges to list its shares on the NSE in February 2017.
The NSE, though, opposed the idea of listing on a rival exchange. Ravi Narain, NSE’s vice-chairman at the time, wrote to SEBI stating that it would prefer SEBI’s oversight rather than BSE’s.
But by then, NSE’s server co-location controversy had become a major regulatory overhang, and its IPO application remained stalled amid the ensuing proceedings. Then came the Chitra Ramakrishna-Anand Subramanian governance row, further casting doubt on the exchange’s quality of management and oversight. It was not until July 2026 that the co-location and dark-fibre matters were settled, with NSE paying nearly ₹15 billion to SEBI.
Given NSE’s history of regulatory and governance controversies, arguing for self-listing may seem counterintuitive. Yet, that is precisely why the issue must be seen as one of regulatory capability rather than institutional trust. As a top global equity market, India must demonstrate its ability to regulate risk rather than eliminate it. That is what the larger, more sophisticated markets in the US and Europe do.
Regulating Conflict
In 2015, when SEBI took the decision to allow India’s stock exchanges to list, the rationale was that it would improve transparency, governance, and price discovery. But it added a caveat: the exchanges could not self-list. The conflict of interest in policing oneself was simply too great; it felt.
Indeed, the 2010 Bimal Jalan Committee appointed to examine the issue had even recommended against the listing of exchanges, arguing that, as public-interest institutions, they must not become speculative financial assets.
The SEBI, after weighing the pros and cons, rejected the no-listing recommendation, concluding that allowing exchanges to list would help make them more transparent and stronger institutionally. It therefore framed a set of rules under which a stock exchange could list.
These included a minimum public shareholding of 51% at all times; fit-and-proper criteria; limits on cumulative ownership of 5% for individuals and 15% for institutions; and the classification of exchanges as infrastructure companies. These remain the current rules.
The case for allowing exchanges to self-list is twofold. First, NSE is overwhelmingly the bigger and more liquid market, so its investors’ interests are better served by its shares being listed on it. Second, and more fundamentally, as financial markets become sophisticated, the regulator’s role should evolve from avoiding conflicts to building the institutional capacity to manage them. That is exactly what regulators in some of the most sophisticated financial markets do today.
Like SEBI, market regulators elsewhere have grappled with the conflict of interest issue, but eventually allowed self-listing with sufficient guardrails. Australia was the first country to do so, when it allowed the Australian Stock Exchange to self-list in 1998. Since then, major exchanges in Singapore, Germany, the UK, Canada, and the US have followed suit.
The US took until 2005 to allow self-listing because, like SEBI, the Securities and Exchange Commission recognised the conflict of interest issue and took time to address it with appropriate regulations.
Once it did, Nasdaq Inc. was allowed to list on Nasdaq in 2005, three years after it first went public on the OTC Bulletin Board. The NYSE Group followed in 2006, beginning trading on the NYSE after its 2005 merger with the electronic marketplace Archipelago.
Institutional Safeguards
The experiences of other stock market regulators offer lessons for India in managing the conflict of interest risk rather than sidestepping it. An exhaustive study is beyond the scope of this column, but a robust regulatory framework can be built around 10 key components.
A separate set of rules for self-listed market infrastructure institutions should supplement existing regulations. Under this framework, a self-listed exchange must have an independent regulatory committee composed entirely of independent directors, with no executive directors or exchange shareholders. Management should not be able to override this committee.
The exchange’s commercial and regulatory functions should be separated. For instance, NYSE Market is the market-operation entity, while NYSE Regulation is a separate, non-profit entity with its own board and CEO. This structure should require independent surveillance of NSE’s own shares.
A chief self-listing compliance officer should report administratively to the CEO or managing director, but report on regulatory matters to the independent committee and SEBI. The officer should be removable only with independent approval from the committee or SEBI.
Exchange executives must also be personally accountable. Every key executive should have specific regulatory responsibilities to fulfil. Any failure should be dealt with swiftly and severely, including disgorgement of all types of remuneration
Independent annual audits should be instituted, with reports going directly to the independent committee and SEBI. Whistleblowers should have direct access to SEBI and protection from management.
The exchange’s own shares must be treated like those of other listed companies it monitors, with no preferential treatment.
SEBI, as the regulator, must retain the ultimate override authority. Any material conflict within the exchange’s structure and framework should be addressed directly by the regulator.
Such a framework would acknowledge that self-listing creates a genuine conflict of interest, while demonstrating that the conflict can be managed through institutional separation, independent oversight, and personal executive accountability.
Perhaps most importantly, it would mark a shift in India’s regulatory philosophy from eliminating conflict to building the capacity to govern it.
More From BasisPoint