.png)

Nilanjan Banik is a Professor at the School of Management, Mahindra University, specialising in trade, market structure, and development economics.
October 21, 2026 at 3:37 AM IST
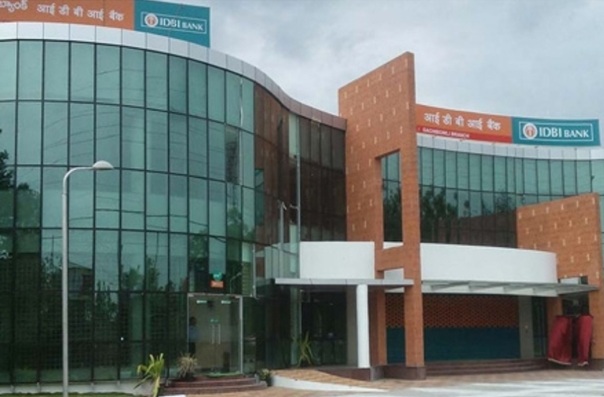
The Union Cabinet’s October 14, 2026, approval to sell the government’s and Life Insurance Corporation of India’s combined 60.72% stake in IDBI Bank to a subsidiary of Fairfax Financial Holdings for approximately ₹528.78 billion marks a significant moment for India’s financial sector. Beyond the scale of the transaction, the proposed sale revives a fundamental debate over the purpose of public ownership: should the state continue to own commercial enterprises simply because it has historically done so?
The answer should depend not on ideology but on public interest. The relevant question is whether retaining ownership delivers greater social value than deploying the same capital elsewhere. Every rupee invested in a government-owned business carries an opportunity cost: it could instead finance healthcare, education, infrastructure, climate resilience or debt reduction. Continued ownership must therefore be justified by the public purpose it serves.
That purpose, however, cannot be defined by profitability alone. The nationalisation of 14 Indian banks with deposits of more than ₹500 million in 1969, for instance, sought to expand banking into rural areas and direct credit towards priority sectors such as agriculture. This developmental role continues through public sector banks’ participation in financial inclusion initiatives such as the Pradhan Mantri Jan Dhan Yojana and the delivery of government benefits under schemes such as the Pradhan Mantri Awas Yojana. Banks mobilise public savings, allocate credit and influence which businesses, sectors and communities gain access to finance. Their decisions affect not only shareholders and customers but also financial stability and the wider economy. These functions illustrate why the state sometimes needs to intervene where markets fail to provide adequate access to essential services or to direct resources towards socially desirable activities that offer limited commercial returns.
The case for public ownership is strongest where national security, critical infrastructure, systemic stability or universal access cannot be adequately secured through other means. But not every enterprise meets this test. A mining company, manufacturer or commercial service provider need not remain under government control merely because it was established with public money. Where competition, regulation and contractual obligations can protect the public interest, continued ownership may be unnecessary.
India’s experience with strategic disinvestmentoffers grounds for examining this distinction. The Economic Survey 2019-2020 studied 11 enterprises disinvested between 1999-00 and 2003-04, including Maruti Suzuki, BALCO, CMC, IPCL, Hindustan Zinc and Tata Communications. Across the group, average net worth rose from about ₹7 billion to ₹29.92 billion, net profit from approximately ₹1 billion to ₹5.55 billion, and gross revenue from ₹15.60 billion to ₹46.53 billion. Returns on assets and equity, as well as productivity, also improved.
Hindustan Zinc provides a notable example: its average net worth increased from around ₹8.18 billion to ₹128.75 billion, while net profit rose from ₹720 million to ₹32.37 billion and revenue from ₹9.99 billion to ₹79.24 billion. These figures do not prove that privatisation is the only path to improved financial performance; outcomes also depend on management, competition and market conditions. India’s New Public Sector Enterprise Policy reflects a similar approach by envisaging a “bare minimum” state presence, including in strategic sectors, and permitting privatisation, mergers or closure elsewhere.
Critics of the IDBI sale argue that public capital helped revive the institution and question whether transferring control to a foreign private group is consistent with priority-sector lending in agriculture and the MSME sector. These concerns deserve serious consideration, but they do not automatically establish that public ownership is indispensable. The question is whether the same objectives can be secured through effective regulation and enforceable commitments. Prudential supervision by the Reserve Bank of India, capital adequacy requirements, competition rules and depositor safeguards are essential. Yet financial inclusion, rural banking access and priority-sector lending also require credible monitoring and clear accountability. If these obligations are to survive a change in ownership, they must be measurable and enforceable, rather than left to general assurances.
The government must therefore justify the IDBI transaction on more than its reported proceeds of ₹528.78 billion. It must demonstrate that the valuation is fair, the buyer is suitable and financial stability will be protected. Equally, it should explain why transferring control offers greater public value than alternatives such as improving the bank’s capital, technology and management while retaining public ownership. The use of the proceeds matters too: a sale can create lasting public value only if the capital released is deployed productively.
The broader lesson is that disinvestment requires a consistent test. Does the state need ownership to exercise essential control? Can regulation protect the public interest effectively? And would the capital generate greater social returns if invested elsewhere? These questions should guide decisions across sectors, while recognising that banking’s role in allocating credit makes its public obligations distinct.
Public ownership is not an end in itself, but neither is privatisation. In the case of IDBI Bank, the central issue is whether the transfer of control can preserve the institution’s developmental responsibilities while improving its capacity to compete.
More From BasisPoint