.png)

The RBI Is Making Haste Slowly
The RBI has settled the direction of rates, not the pace. A cautious inflation diagnosis faces a harder test from the dollar and financial risks.
Kalyan Ram, a financial journalist, co-founded Cogencis and now leads BasisPoint Insight.
October 7, 2026 at 6:39 AM IST
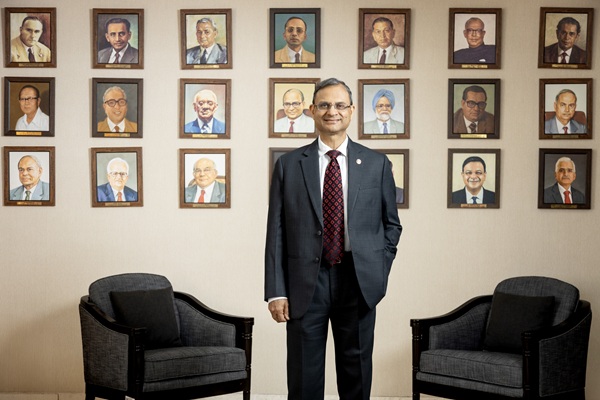
The Reserve Bank of India has settled the direction of interest rates without settling how urgently it needs to travel. Its October decision raises the repo rate by 25 basis points to 5.50% and rules out near-term cuts, but Governor Sanjay Malhotra’s language remains more guarded than “calibrated tightening” might suggest. The direction is firmer than the diagnosis, leaving markets to judge whether this is prudent caution or an insufficient response.
Malhotra describes the increase as a recalibration made necessary by an inflation outlook that is no longer as benign as last year’s. With headline inflation expected to average close to 6% over the current and following two quarters and core inflation projected at 4.4% this financial year, the justification for retaining the old rate has weakened. The statement does not, however, establish that an aggressive sequence of increases is now required.
Its qualifications are revealing.
There is some evidence of elevated inflation expectations and generalisation, yet signs of supply pressures becoming embedded in firms’ pricing behaviour remain limited. Broader inflation can reflect the indirect effects of higher input costs without proving that a persistent second-round process has developed. The RBI is acting before that distinction becomes clear, while declining to treat the two as interchangeable.
Demand presents a similar ambiguity, in Malhotra’s words. Strong monetary and credit expansion creates risks, but the committee finds only limited evidence of demand-side pressures. This is a recalibration, not an admission that the economy is overheating. Calling it merely a belated catch-up would therefore miss part of the rationale, although the repeated qualifications leave open how much evidence the RBI will require before moving again.
The stance narrows that uncertainty without eliminating it. Calibrated tightening permits hikes and pauses, not near-term cuts. It neither commits the committee to consecutive increases nor declares that real rates must become restrictive. The 4–2 division on the stance, against unanimity on the hike, places the disagreement over tomorrow’s policy options rather than today’s adjustment. It is best not to confuse agreement on direction with agreement on urgency.
Limits to Domestic Orientation
The external setting nevertheless makes the cost of caution harder to dismiss. Malhotra himself identifies an appreciating dollar, elevated global bond yields, and tighter financial conditions. The accompanying Monetary Policy Report projects growth of around 7% and inflation of around 5% in 2027–28. That combination hardly suggests an economy requiring prolonged protection from higher nominal rates, particularly if US rates remain elevated.
Those forecasts cannot identify a neutral real rate, but they raise the burden of explanation for a shallow cycle. A limited adjustment would need to be consistent with returning inflation towards 4%, rather than merely stabilising it at a higher level. The absence of overheating is not, by itself, sufficient justification for stopping.
India need not follow the Federal Reserve or use interest rates to defend a particular exchange rate. But policy independence does not remove the external constraint. A stronger dollar and persistently high US rates can pressure financing conditions even without a deterioration in domestic activity. A quarter-point increase need not unsettle currency positions built around that global view. Its effect depends partly on whether investors believe the RBI will sustain its response as risks evolve.
The Governor’s warning about AIvaluations adds a risk that cannot be answered by an inflation forecast. A sharp correction could transmit through portfolios, capital flows, and funding appetite, bringing financial stress to economies whose domestic growth remains sound. This is not an independent argument for higher Indian interest rates, but it exposes the limits of reading policy solely through domestic price pressures. Such disruption could arrive well before the inflation data resolve the uncertainties on which the RBI’s cautious diagnosis still rests.
Financial stability consequently requires a credible inflation response alongside the capacity to manage market disruption. A global asset-price correction could require liquidity support rather than additional restraint, even while the policy rate remains high. The RBI needs room to distinguish a threat to market functioning from a reason to abandon its inflation objective.
For now, the immediate operational test is less dramatic.
Malhotra’s commitment to align the weighted average call rate with the repo rate must ensure that surplus liquidity does not soften the increase. The absence of a fresh reserve requirement is not itself evidence of lack of resolve; failure to transmit the higher rate would be. Judgement should rest on financial conditions, not the number of instruments announced.
The RBI has retained flexibility, not secured an exemption from acting promptly. Its cautious diagnosis is defensible because generalisation is not yet proof of entrenched inflation, but the external risks it identifies argue against waiting for proof beyond reasonable doubt. Making haste slowly can be a coherent strategy only if the pace changes when the evidence does. Otherwise, recalibration risks becoming a recurring explanation for a policy setting that keeps needing to catch up.
More From BasisPoint