.png)

Cost of Sustainability Must Not Become the Cost of Digital Exclusion
India’s new UPI merchant fee framework seeks to make digital payments sustainable, but policymakers must ensure higher costs do not push small merchants back towards cash.
Dr. Mishra is former Executive Director of RBI and the Founder Director of its College of Supervisors. He is currently RBI Chair Professor at Gokhale Institute of Politics and Economics.
Komal Gupta is the Founder & Principal Consultant, Konsult Komal. She works extensively in the areas of corporate governance, especially in the cooperative sector
October 13, 2026 at 11:44 AM IST
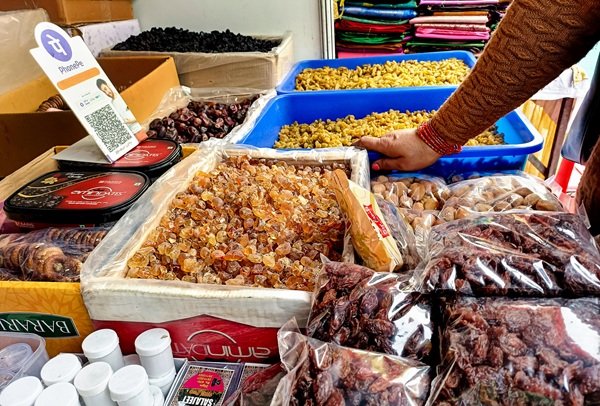
A tea seller accepting ₹10 through a QR code, a cobbler receiving ₹35 without asking a customer for change, or a roadside food vendor collecting payments digitally may appear to be small illustrations of India’s UPI revolution. These are, in fact, central to understanding its economics. For many such merchants, digital payments did not replace credit cards or debit cards. They replaced cash. The use of cash was reduced.
That distinction matters, as India prepares to reintroduce merchant charges on selected Unified Payments Interface transactions. The debate is often framed as a choice between free digital payments and a financially sustainable payments system. The economics are more complicated. UPI infrastructure has costs, but so does discouraging merchants from accepting digital payments. The challenge is to find a funding model that recognises both.
UPI was never simply a story of “free” payments
UPI was launched by NPCI in April 2016 and went live later that year. In its early years, merchant transactions operated within an MDR framework. The Government subsequently used incentives and reimbursements to reduce the cost of digital payments.
In December 2017, the Union Cabinet approved government reimbursement of MDR on debit-card, BHIM-UPI and Aadhaar Enabled Payment System transactions up to ₹2,000 for two years from January 2018. The rationale was straightforward: MDR was a cost for merchants and could discourage acceptance of digital payments when cash remained an alternative. The Government therefore reimbursed banks for the MDR rather than leaving the merchant to bear it.
The policy changed more fundamentally from January 1, 2020. Until December 2019, the Government had reimbursed MDR on qualifying transactions up to ₹2,000. From Jan 1, 2020, no charge, including MDR, was to apply to payments made through prescribed electronic modes, including RuPay debit cards, BHIM-UPI and BHIM-UPI QR codes. The RBI subsequently recorded this transition from the earlier reimbursement mechanism to the broader zero-MDR framework.
Zero MDR, however, did not make the underlying payment infrastructure costless. Public support continued through incentive schemes for RuPay debit-card and BHIM-UPI transactions. Government payouts under these schemes rose from ₹13.89 billion in 2021-22 to ₹22.10 billion in 2022-23 and ₹36.31 billion in 2023-24. Of these amounts, BHIM-UPI accounted for ₹9.57 billion, ₹18.02 billion and ₹32.68 billion, respectively.
The distinction matters. Zero MDR did not mean zero economic cost. It meant that the merchant was not directly charged MDR under the applicable framework. The costs of operating and sustaining the payment ecosystem continued to be borne by other participants and, increasingly, through public support. The 2026 framework therefore represents not the introduction of cost into a previously costless system, but another change in how UPI's costs are allocated across the ecosystem.
The 2026 framework changes the model once again
A 0.4% MDR was due to apply from October 15, 2026, to specified P2M transactions above ₹2,000, subject to prescribed caps and exemptions. NPCI deferred the rollout on October 13, 2026, and said the charge would instead take effect after Diwali on a date to be notified separately. Transactions up to ₹2,000 would remain free, as would transactions covered by the zero-MDR provision for qualifying small merchants. Specified essential and thin-margin sectors would face a flat ₹5 MDR above ₹2,000, while capital-market transactions would attract a lower rate.
The Government has said that about 96% of P2M transactions would be unaffected. It has also clarified that MDR is neither a tax nor a charge collected by the Government or NPCI. It is distributed among participants in the payment ecosystem.
Calling it a “UPI tax” is therefore technically wrong. But after years of zero MDR, introducing a charge changes the economics of accepting some digital payments. The important question is who bears the cost, who receives the revenue and what economic problem the revenue is intended to solve.
Under the announced framework, 40% of the MDR would go to the issuing bank, 30% to the merchant acquirer, 20% to the third-party UPI application provider and 10% to the application’s bank partner. On a ₹10,000 eligible transaction, the ₹40 MDR would translate to ₹16, ₹12, ₹8 and ₹4, respectively.
This is ecosystem revenue, not government revenue. That makes understanding its economic basis important.
The merchant’s counterfactual matters
The incidence of the fee matters as much as its aggregate recovery.
For a large retailer that already accepts cards, the relevant comparison may be between two digital payment instruments. For a roadside vendor, UPI may be replacing cash. A 0.4% charge is therefore not simply a shift between competing digital payment methods. It can represent a new cost attached to a payment method that previously carried no direct MDR for the merchant.
The policy debate needs to move beyond aggregate transaction values. A ₹10,000 digital payment may generate more MDR revenue than ten ₹1,000 payments, but transaction size alone does not indicate whether the merchant is a large retailer, a small business making an occasional high-value sale, or a micro-enterprise with thin margins.
The relevant counterfactual is therefore not simply how much MDR can be recovered, but what happens to merchant behaviour when the cost of accepting UPI changes. If some merchants respond by shifting customers towards cash or other payment instruments, the revenue recovered by the ecosystem may come with a corresponding cost to digital adoption.
The policy therefore needs to distinguish between the economics of the payment ecosystem and the economics of the merchant. Both matter to the sustainability of UPI.
What should happen next?
First, MDR should not be treated as a uniform economic burden across merchants. Transactions above ₹2,000 account for only about 4% of P2M transaction volume but around 67% of transaction value, according to a Business Standard analysis based on NPCI data. This concentration warrants a more differentiated approach to MDR, based on observable transaction and merchant-level payment patterns rather than transaction value alone.
Second, merchant-to-merchant transactions require clear treatment. A business payment within a supply chain is economically different from a consumer purchase. The framework should therefore establish clear rules for identifying and treating M2M transactions, rather than leaving merchants and payment providers to interpret their treatment.
Third, the recommendation to create a pool equivalent to 5% of MDR collections to support small merchants should be outcome-based. Its effectiveness should be measured not by QR-code installation, but by sustained digital acceptance, fraud awareness, grievance redress and payment reliability.
Finally, the P2PM framework itself merits closer examination. The current threshold provides a simple administrative test for protecting smaller merchants, but monthly UPI receipts are not necessarily the same as turnover, profitability or business size. A merchant crossing the threshold because of seasonal or temporary transactions should not necessarily be treated in the same way as one with persistently higher receipts. How P2PM can be made more responsive to these differences is a separate policy question that deserves deeper examination.
India has already used several models to finance digital payments: Government reimbursement, zero MDR and ecosystem incentives. The proposed MDR framework is the latest iteration of that policy journey. The question is therefore not whether UPI should have an economic model. It must. The more important question is whether that model allocates costs in a manner that is economically defensible without weakening merchant acceptance.
UPI succeeded partly because it made digital payment acceptance simpler than handling cash. The policy challenge now is to ensure that making the system financially sustainable does not make accepting it economically unattractive.
(This is Part 1 of a two-part series on UPI’s MDR debate. Part 2 examines whether the current P2PM framework adequately protects small merchants as digital payment volumes rise.)
More From BasisPoint