.png)

Sharmila Kantha is an industrial policy specialist and author. Formerly a consultant at the CII*, she has worked extensively on economic policy and India’s international engagement.
September 18, 2026 at 11:37 AM IST
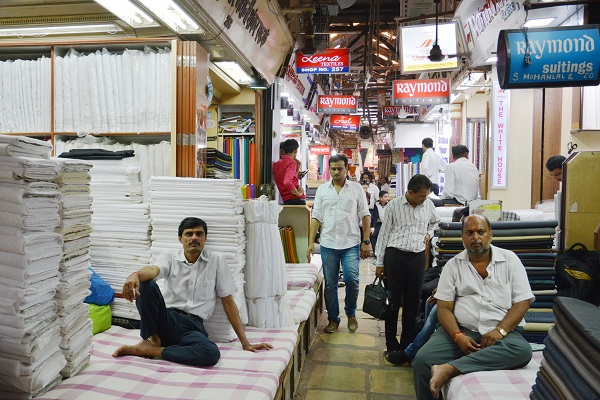
The government has often stressed that youth should shift from being ‘job seekers’ to ‘job creators’. As the Annual Survey of Unincorporated Sector Enterprises, or ASUSE, data shows, India is home to a large number of establishments, but these are largely tiny, one-person units operating at subsistence level. Scaling up even a small proportion of them would need a range of policy interventions, including easy access to credit.
ASUSE estimated the total number of enterprises at 79.25 million as of 2025, up from 59.7 million in the 2021-22 survey. Only about 10 million enterprises hire any workers, including unpaid family members. These establishments provided livelihood to as many as 128 million workers, of which 82 million worked in their own enterprises and 46 million in units that hired workers.
The establishments address hyperlocal economies and markets, with limited scope for scale. Raising their productivity and incomes demands targeted policies in the different sectors in which they operate. Access to credit is a key enabler for working capital, access to inputs, connectivity to markets and skilling.
ASUSE data does not provide information on outstanding credit per establishment. Encouragingly, 82.5% of the establishments operated bank accounts, and commercial banks remain the chief source of credit at 61% of outstanding loans. The rest comes from central- and state-level term-lending institutions and government schemes, cooperative banks, microfinance and other institutional and non-institutional agencies.
Fortunately, money-lenders seem to have low clout at just 2.2% of the loan book, but loans from friends and relatives contribute close to 5%.
Data from the Reserve Bank of India shows that credit to the micro and small sector almost doubled in value between March 2022 and March 2026. The MUDRA Yojana, a flagship scheme for collateral-free credit for small businesses, has emerged as a vital source of funds. Over 11 years of operations since 2015, the scheme sanctioned close to 600 million loans totalling ₹40 trillion, with the annual sanctioned amount going up four times in this period.
About three-fourths of these loans went to the Shishu category of loans of up to ₹50,000, not enough for meaningful expansion. According to SIDBI, units with a credit exposure of ₹200,000 to ₹1 million saw a slow 5% CAGR in outstanding balances in the last three years.
The significant effort in connecting credit with tiny units through the MUDRA scheme is unfortunately not reflected in higher enterprise productivity. In fact, the gross value added per establishment increased by a mere 12% between 2021-22 and 2025. Further, this varies greatly between establishments. Those that hired workers saw GVA at about ₹1 million in 2025 while the own-account establishments reached barely ₹140,000.
While several other schemes such as the credit guarantee scheme, PM Employment Generation Programme, and Self-Reliant India Fund have been instituted, these add up to low coverage in general. A 2022 report from the Standing Committee on Finance estimated MSME credit gap at ₹20 trillion-₹25 trillion.
The first requirement would be to increase the quantum of the loans and ensure that they are accessible to informal establishments without collateral. The annual sanctioned amount at about ₹5 trillion-₹6 trillion is clearly insufficient as per the credit gap and can be raised through a dedicated fund, perhaps housed in SIDBI.
Two, a targeted credit support programme would need to be tailored to different sectoral operations. ASUSE data shows that since the first such survey of 2021-22, the share of enterprises engaged in manufacturing and trading has declined and that of ‘other services’ expanded by 2025. Notably, much of the rise has been in the sub-sector of community, social and personal services, probably since this requires low initial investments, low skill levels and minimal inputs. It would be important to offer loans to sub-sectors that show higher productivity with the potential for greater incomes.
Further, the decline in manufacturing establishments is of concern and credit efforts need to be directed towards productive capital spending for this purpose. Similarly, the loan size limits can be enhanced.
Finally, an important aspect would be to build financial and management capacity for the owners and workers running these tiny units. With smart phones in their hands, digital skill capsules can be delivered to enable them to seek opportunities, access capital, repay loans, and enhance productivity and incomes.
The ASUSE data throws up a thick layer of struggling business units delivering low productivity, employment and incomes. While financial access has increased, the quantum of loans falls short to enable a restructuring of this sector from subsistence level to ‘job creator’ level. A strong drive to push credit towards these units in a targeted manner will help the unorganised sector to move into more productive establishments.
More From BasisPoint