.png)

Asian Markets Fall as Nvidia Selloff Weighs on Tech Stocks
Here’s your quick read to start the day: a chatty, no-fuss look at overnight moves, the big story, what’s on the docket, and the tickers you need to watch.
November 17, 2026 at 2:24 AM IST
Global Mood: Cautiously risk-off
Asian markets opened lower on Tuesday, with Japan’s Nikkei 225 down 0.76%, Topix falling 1.06%, South Korea’s Kospi declining 1.57% and Australia’s S&P/ASX 200 losing 1.37%. Selling pressure extended across AI-linked stocks, including AMD, Micron Technology and Sandisk, amid concerns over Nvidia’s outlook and leadership uncertainty. Nvidia shares have fallen nearly 24% this month, putting them on track for their steepest monthly decline since April 2022.
US stock futures were largely unchanged on Monday night after Wall Street closed lower, with Dow futures up 0.02%, S&P 500 futures gaining 0.06% and Nasdaq-100 futures rising 0.1%. Nvidia led losses in the technology sector, falling 4.1% ahead of its fiscal third-quarter results after Tuesday’s market close. The GIFT Nifty was trading at 25,320, up 24.5 points or 0.10%, pointing to a mildly positive opening for Indian equities.
THE BIG STORY
Ukraine launched its largest overnight drone attack on Russia since the start of the war in 2022, with Russian defence ministry data showing 1,336 drones intercepted across 16 regions. Around 600 drones were directed towards the Moscow region, while the Crimean Bridge and areas hosting oil refineries were also targeted.
The attacks caused fires at industrial facilities in the Rostov and Krasnodar regions, including areas near oil refineries.
Ukrainian President Volodymyr Zelenskiy said the strikes had significantly reduced Russian refining capacity, while industry sources previously estimated a 30% decline.
The escalation comes despite renewed US-led peace efforts, with both sides continuing attacks on energy and strategic infrastructure. US envoy Jared Kushner said progress was being made towards an agreement to end the Ukraine war following discussions with Russian, Ukrainian and European representatives.
He described the latest engagements as productive but said significant challenges remained and a final agreement would require difficult decisions.
Nvidia's board is not considering reinstating former CEO Jensen Huang despite a growing campaign calling for his return following his resignation over revelations of personal relationships and alleged links to Chinese intelligence. More than 180,000 people have signed a petition seeking Huang's reinstatement, with Elon Musk and several prominent technology executives backing the campaign. US President Donald Trump also said he would not mind seeing Huang return.
However, investors and governance experts have warned that reinstating him before investigations are completed could expose the company to further risks.
Data Spotlight
The NY Empire State Manufacturing Index fell to 7.8 in November from 25.5 in October, missing expectations of 18. The index dropped to 3 from 23.2, while shipments eased to 8.8 from 13.1, indicating slower business activity.
The employment index rose to 18.1, its highest in more than four years. Capital spending plans and business optimism also improved. Eurozone industrial production rose 0.2% month-on-month in September, ending three consecutive months of contraction but missing expectations of 0.3%.
Germany led industrial production, which increased 1.3%, while Italy and Spain recorded gains of 1.2% and 0.9%, respectively. France remained weak as industrial production fell 0.5%, marking a fifth consecutive month of contraction or stagnation. Eurozone output was down 1.5% year-on-year.
Japan's GDP unexpectedly stagnated. The economy recorded zero quarter-on-quarter growth in Q3, missing expectations of 0.1% and slowing from 0.4% in Q2.
Consumption and trade weighed on growth. Private consumption fell 0.3%, while net trade subtracted 0.6 percentage points as exports declined 0.2% and imports rose 2.5%. Business investment offered support. Investment increased 1.6%, recovering from a 0.4% contraction in the previous quarter.
Takeaway: Global growth indicators remain mixed. Slower US manufacturing activity and Japan's unexpected stagnation point to weakening momentum, while the Eurozone's return to industrial growth offers some relief. However, persistent weakness in parts of Europe and subdued Japanese consumption suggest the recovery remains fragile.
WHAT HAPPENED OVERNIGHT
US Stocks Fall Sharply as AI Concerns Mount Ahead of Nvidia Results, Anthropic IPO
- US stocks ended sharply lower on Monday as concerns over the artificial intelligence sector weighed on technology shares ahead of Nvidia's quarterly results on Tuesday and Anthropic's expected initial public offering later this week.
- The Dow Jones Industrial Average fell 1.41% to 51,608.17, the S&P 500 declined 1.92% to 7,416.59 and the Nasdaq Composite dropped 2.49% to 24,509.76.
- The Philadelphia Semiconductor Index plunged 5.3%.
- Nvidia shares fell 4.1%, extending recent losses following chief executive Jensen Huang's resignation.
- Intel and Micron dropped more than 7% each, while CoreWeave and Nebius fell 6.1% and 7.6%, respectively.
- The Trump administration also issued new restrictions aimed at limiting China's access to advanced AI chips.
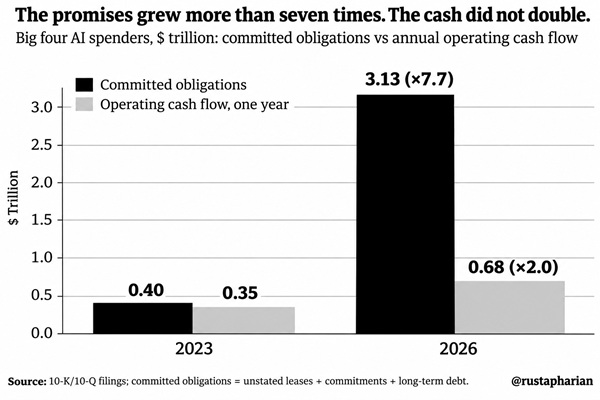
- Investors are awaiting Nvidia's results for clues on the sustainability of AI-related investment, while Anthropic's IPO is expected to test appetite for the sector. Analysts expect Nvidia's earnings to rise by 90.4% year on year, on revenue of $109.10 billion.
US Dollar Hits 20-Month High as Fed Rate Hike Bets Strengthen; Euro Weakens
- The US dollar index rose to 103.40 on Monday, its highest level in nearly 20 months, as persistent inflationary pressures reinforced expectations of further Federal Reserve rate hikes.
- Recent consumer and producer inflation data showed that higher energy prices were feeding into underlying price pressures, prompting Fed officials to signal that tighter financial conditions may be needed to curb inflation.
- The dollar also gained against the Canadian currency after one of Canada's core inflation measures unexpectedly declined.
- Meanwhile, concerns over France's fiscal position fuelled fears of contagion across eurozone sovereign debt markets, weighing on the euro.
US 10-Year Treasury Yield Nears One-Month High at 5.15% as Fed Rate Hike Bets Firm
- The yield on the 10-year US Treasury note hovered near 5.15% on Monday, testing its highest level in a month as persistent inflation and a resilient economy strengthened expectations of further Federal Reserve rate hikes.
- Markets fully priced in a 25-basis-point rate increase next month, with further hikes expected next year.
- US core consumer inflation rose more than expected in October, suggesting higher oil and fuel costs were feeding into underlying services prices.
- Continuing jobless claims also fell to their lowest level in more than three years, pointing to resilience in the labour market.
- Treasury securities failed to benefit from safe-haven demand amid the ongoing selloff in AI infrastructure stocks, as funds reportedly liquidated fixed-income positions to raise cash.
Oil Falls More Than 3% as Recovering West Asian Exports Strengthen Supply Surplus Outlook
- Oil prices settled more than 3% lower on Monday as recovering crude flows through the Strait of Hormuz reinforced expectations of a global supply surplus, outweighing concerns over fresh tanker incidents.
- Brent crude fell $3.40, or 3.6%, to settle at $92.44 a barrel, while US West Texas Intermediate declined $2.84, or 3.2%, to $85.72.
- The International Energy Agency expects global oil supply to exceed demand by 1.7 million barrels per day in the fourth quarter, with supply averaging 105 million bpd as exports from West Asia recover.
- Goldman Sachs forecasts Brent to average $88 a barrel next year and fall to $78 by December 2027.
- Demand concerns in China also weighed on prices, with refinery throughput falling 2% month on month and 8.1% year on year in October.
- Reuters estimates indicated that Chinese crude inventories rose by 492,000 bpd last month.
- However, geopolitical risks persisted after Iran's Revolutionary Guards said six tankers caught fire in the Strait of Hormuz on Sunday and Monday, including two allegedly struck by mines. Reuters could not independently verify the reports.
Day’s Ledger*
Economic Data
- UK September Unemployment Rate
- German November ZEW Economic Sentiment
- US October Retail Sales
- US October Industrial Production
Policy
- US Fed Waller Speaks
Corporate Actions
- Earnings: Libas Consumer Products
Tickers to Watch
- SENCO GOLD Posts the highest-ever retail NSV of over 24.26 billion rupees in the 41-day Dhanteras-Diwali period (October 1-November 11, 2026). Up 26% YoY despite a 17% rise in gold prices. Retail revenue up 25%. SSSG at 17%. The April-September 2026 topline crosses 50 billion rupees. Trailing 12-month sales top 100 billion rupees.
- HDFC LIFE INSURANCE COMPANY approves raising to 5 billion rupees via subordinated NCDs on private placement. The issue is of up to 47,500 debentures, each with a 100,000-rupee face value.
- ADANI ENTERPRISES Adani Wind starts producing India's longest onshore wind turbine blades, at 91.2 metres, at its Mundra facility. Also certifies its MWL185-5.0 MW turbine platform for serial production.
- ANAND RATHI WEALTH promoter and Chairman Anand Rathi to gift up to 125,000 shares (about 0.08% equity) to around 5,000 individuals. The shares are worth about 300 million rupees. Each recipient gets up to 25 shares. Recipients include employees and personal staff.
- BSE US CFTC approves offer and sale of BSE BANKEX Index Futures to US investors after a 45-day expedited review.
- CAPRI GLOBAL CAPITAL gets shareholder approval to raise to 40 billion rupees. Routes include equity, debt, warrants, rights issue, QIP, FCCBs and ECBs.
- HERO MOTORS signs shareholders' agreement with UK subsidiary Hewland Engineering and its existing shareholders on November 16, 2026. Follows earlier approval to buy 8,039 shares in HEL for about £0.60 million.
- VEDANTA clarifies that the Supreme Court's ruling on the Videocon Industries resolution plan does not pertain to it. Says it was not a party to the proceedings. Shares fell nearly 3% in morning trade on the reports.
Must Read
- Banking Regulation: Is the Timing of the Accounting Reset Right?
- The Guarantor of Last Resort
- The Republic of Headcounts: Why India's Informal Earners Have Been Left Behind
- Pay for the Product, Then Pay to Advertise the Seller?
- Foreign Investors Want More Than a Tax Cut and India Needs to Listen
- From Enron to now Escrow, India’s Search for Capital Protection
- CBDT chief says LTCG, STT proposals under review ahead of Union Budget
- India braces for higher interest rates as inflation, oil prices rise
- India central bank tells Tata Sons to comply with listing rule, letter shows
- India's markets regulator forms panel to simplify capital-raising rules
(*Compiled from various media sources)
See you tomorrow with another edition of The Morning Edge.
Have a great trading day
More From BasisPoint