.png)

Indian Equities Rebound Tracking Lenders, Payment Firms; Oil, US Fed Caution Limit Gains
An end-of-day recap of all that transpired in the Indian markets, highlighting the major price movements and the factors driving them
September 16, 2026 at 12:37 PM IST
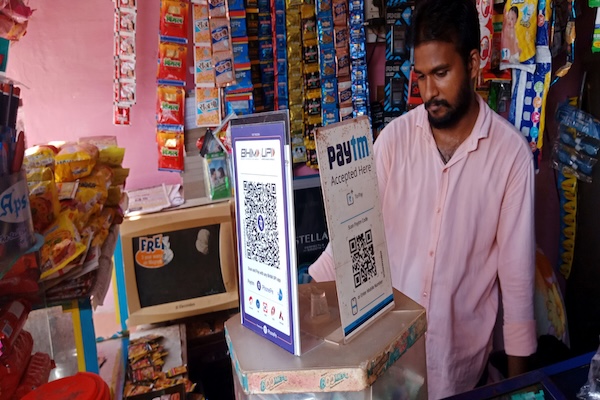
Benchmark Indian equity indices recovered on Wednesday after their recent slide, led by lenders and payment firms following the government’s decision to impose a fee on certain UPI transactions. The Nifty50 rose 0.43% to 23,217.60, while the Sensex gained 0.45% to 74,336.45.
Gains were capped by elevated oil prices, worsening West Asia tensions and caution ahead of the Federal Reserve’s policy decision. Twelve of the 16 major sectors advanced today.
Banks, private lenders, public-sector banks and financial-services stocks gained between 0.7% and 1.5%. Paytm rose 3.5%, while ITC, Nestle India and Tata Consumer Products were among the top Nifty 50 gainers. The Nifty FMCG, PSU Bank and Realty indices outperformed, whereas Nifty IT and Pharma underperformed. In broader markets, the Nifty MidCap index rose 0.14%, while the SmallCap index fell 0.15%.
Brent crude traded around $108 a barrel as supply risks intensified after Saudi Arabia suspended oil loading at Yanbu port and reduced shipments to Europe. Elevated energy prices continued to raise concerns over inflation and India’s external balances, limiting the upside in equities.
The Indian rupee ended flat at 95.9550 per US dollar after touching 95.9750, its weakest level since July 27. Strong dollar demand from local companies and expectations of a rate hike by the US Federal Reserve weighed on the currency, while likely intervention by the Reserve Bank of India helped limit losses.
Indian government bonds recovered from early losses to end higher as private banks bought at elevated yields, while traders remained cautious ahead of the Federal Reserve’s policy decision. The benchmark 6.94%, 2036 bond yield eased to 7.0524% from 7.0727%. Trading volumes remained thin, with market participants awaiting the Fed’s rate decision and guidance on the policy path.
Top Movers of the Day
Tata Investment Corporation fell 5.20% to ₹681 after a sharp run-up on Tuesday following the Reserve Bank of India’s rejection of Tata Sons’ plea to exit its NBFC status. The stock faced heavy profit-taking as investors booked gains after the recent rally.
PNC Infratech fell 5% to ₹133.30, extending its recent correction after a strong rally in prior sessions. The shares have been falling since Tuesday after NHAI and MoRTH imposed a three-year ban on assigning new projects to the company.
Sterlite Technologies declined 4% to ₹818.50 as investors reduced exposure to high-beta technology, media and telecom, and optical-fibre stocks amid elevated yields and crude prices.
HEG fell 3.71% to ₹217 due to a technical price adjustment on the demerger record date, when its core graphite business was transferred from HEG Advanced Materials to HEG Graphite.
Groww, or Billionbrains Garage Ventures, fell 3.92% to ₹190 after around 100.7 million shares changed hands in a block deal. The large secondary transaction created immediate supply pressure, although no change in fundamentals was reported.
Kanohar Electricals listed at ₹672.05 on the BSE and ₹685.50 on the NSE, an 8% premium to its ₹632 IPO price. The electrical-equipment SME made a modest debut amid volatility in the broader market.
Dr Lal PathLabs fell close to 1% to ₹1,887.80 on profit-booking and minor sector wide downward pressure near its recent highs.
Apollo Tyres rose 1.42% to ₹411.95 amid selective buying in auto stocks and expectations of steady replacement demand, despite weakness in the broader market.
Yes Bank advanced 1.21% to ₹23.35 in early trade amid heavy volumes and retail participation. The stock benefited after major brokerages identified Yes Bank as a key beneficiary of new UPI fee rules.
Zensar Technologies gained 2.79% to ₹452.50 as investors sought value in mid-cap IT stocks following the sector’s recent correction. No major company-specific trigger was reported.
BHEL and Bharat Forge remained in focus following recent order wins and expectations of defence and industrial capital expenditure. Both stocks attracted selective buying, although gains were limited by broader market weakness and profit-taking in PSU and capital-goods counters.
Futures & Options
The Nifty September 2026 futures closed at 23,282, a premium of 64.4 points over the Nifty 50’s cash-market close of 23,217.60. The Nifty 50 gained 99 points, or 0.43%, during the session, while the NSE’s India VIX, a gauge of expected near-term volatility, fell 1.58% to 13.22.
HDFC Bank, Patanjali Foods and One 97 Communications (Paytm) were the most-traded individual stock futures contracts on the NSE. The September 2026 F&O contracts will expire on September 29, 2026.
Bonds
Indian government bonds recovered from early losses to end higher on Wednesday as private banks bought bonds at elevated yield levels. The buying supported prices and pushed the benchmark yield lower, although trading remained subdued ahead of the US Federal Reserve’s policy decision.
The benchmark 6.94%, 2036 bond yield ended at 7.0524%, down from 7.0727% in the previous session. The yield had eased to 7.0597% earlier in trade.
Some traders positioned for the possibility that the Fed could hold rates, citing uncertainty around the policy outlook ahead of the US midterm elections in November. However, the CME FedWatch tool indicated a 92.5% probability of a rate hike at the policy outcome, due after Indian market hours.
Most market participants remained cautious, with the Fed’s decision and forward guidance expected to provide fresh cues for domestic bond yields.
Forex
The Indian rupee ended flat at 95.9550 per US dollar on Wednesday after touching 95.9750 intraday, its weakest level since July 27. Strong dollar demand from local companies and expectations of a US Federal Reserve rate hike weighed on the currency, while likely intervention by the Reserve Bank of India helped limit losses. The rupee has remained above the 96-per-dollar level in recent sessions amid persistent support from the central-bank.
Brent crude eased modestly but remained above $100 a barrel, while the US dollar index held near multi-week highs and regional currencies were mostly subdued. Investors awaited the Federal Open Market Committee statement and Fed Chair Kevin Warsh’s press conference for guidance on whether the expected rate hike would be sufficient or followed by further tightening.
Crypto
The cryptocurrency markets came under renewed selling pressure on Wednesday as regulatory disappointment and macroeconomic uncertainty prompted investors to reduce exposure to high-volatility assets. Bitcoin traded near $75,870, while Ethereum fell to around $2,400 as both tokens struggled to hold recent support levels. Trading volumes increased amid intensified selling across major exchanges.
Sentiment weakened after the US Senate failed to advance the Digital Asset Market Clarity Act, renewing concerns over the timeline for regulatory clarity in the digital-asset sector. The setback coincided with caution ahead of the Federal Reserve’s policy decision, with markets expecting a potential rate hike to counter persistent inflation pressures exacerbated by elevated oil prices. Higher borrowing costs and a stronger risk-off environment weighed on non-yielding crypto assets.
US Stock Futures
US stock futures edged higher early Wednesday as investors awaited the Federal Reserve’s interest-rate decision, which could signal the start of a new rate-hike cycle over the coming months. S&P 500 futures rose 0.2%, Nasdaq-100 futures gained 0.4% and Dow futures were up 58 points, or 0.1%.
Markets were pricing in a 92.5% probability of a 25-basis-point rate hike at Wednesday’s meeting. The probability of another quarter-point increase stood at 45% for October and 30% for December. The Fed’s current target range is 3.5%–3.75%. Meanwhile, US consumer-price inflation eased to 3.4% in August from a recent high of 4.2% in May.
US Treasury Notes
US Treasury note yields held near multi-year highs early Wednesday as investors positioned for the Federal Reserve’s interest-rate decision later in the day. The benchmark 10-year Treasury yield was little changed at 4.998%, easing from Tuesday’s intraday peak of 5.04% and remaining near its highest level since July 2007. The two-year yield fell to 4.65% after touching a cycle high of 4.68%.
Trading remained subdued ahead of the policy announcement, with markets pricing in around a 92% probability of a 25-basis-point rate hike. Elevated oil prices near $108 a barrel continued to fuel inflation concerns, while expectations of further rate increases kept pressure on the front end of the Treasury curve.
Top News
- India, Pakistan naval ships collide in Arabian Sea; Delhi lodges protest
- UPI gets MDR: How 0.4% merchant fee compares with debit, credit cards
- India, others face 100% tariffs as US House advances Russia sanctions Bill
- India remains key driver for global growth: IMF Deputy MD Nigel Clarke
- Indian economy at inflection point, needs growth rethink: CEA Nageswaran
- India cabinet clears plan to raise EPF wage upper limit to 25,000 rupees
- Traders brace for prolonged India bond slump as RBI mops up excess cash
- India eases export rules, waives registration for small exporters
- Apple takes margin hit on iPhone 17 to keep India price competitive
- India's Hero Motors IPO fully subscribed on opening day
- India likely to extend key export incentive for five years, source says
- India's NSE to launch IPO amid investor caution over derivatives-fuelled growth
- Gold rises on easing dollar, oil as Fed rate verdict looms
More From BasisPoint